
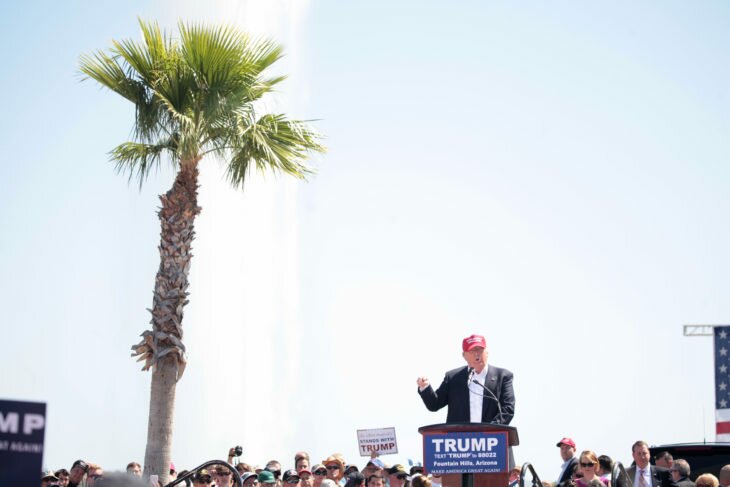
Today, Donald Trump is in Anaheim, California, where the housing crisis that he rooted for devastated families and communities, leading to the loss of more than 1 million jobs and pushing more than half a million Californians out of their homes.
Before the economic crisis in 2008, Trump said he was “excited” for the housing market to crash and bragged that he could make lots of money off of a housing crisis. Yesterday, Trump doubled down on his comments, saying that his plans to profit off of foreclosures was “the kind of thinking our country needs.” While Trump may have benefitted from the housing crisis, it meant terrible job losses, lost homes and financial ruin for hundreds of thousands of California families.
TRUMP ROOTED FOR THE REAL ESTATE BUBBLE TO BURST
2007: Donald Trump: “I’m excited if” the real estate bubble is about to burst because “I’ve always made more money in bad markets than in good markets.”
Mr. Trump said he is poised to invest in depressed property as the downturn moves through individual cities. ‘People have been talking about the end of the cycle for 12 years, and I’m excited if it is,’ he said. ‘I’ve always made more money in bad markets than in good markets.’
2006: Donald Trump: “I sort of hope” the housing market collapses “because then people like me would go in and buy.”
Two years before the housing market collapsed in 2008 and millions of Americans lost their homes, Donald Trump said he was hoping for a crash. ‘I sort of hope that happens because then people like me would go in and buy,’ Trump said in a 2006 audiobook from Trump University, answering a question about ‘gloomy predictions that the real estate market is heading for a spectacular crash.’
REAL ESTATE BUBBLE BURSTING HURT CALIFORNIA
Home prices in California dropped 6.6% between the end of 2006 and the end of 2007, the largest fall in 25 years.
In 2007, California home prices suffered the fastest and steepest decline in 25 years. California home prices fell 6.6% between the fourth quarter of 2006 and the fourth quarter of 2007. (Just two years ago, home prices rose 21% in California.) Nationally, home prices rose 0.8%, well ahead of California but the slowest national growth since 1990.
Areas in California’s northern San Joaquin Valley saw decline in housing prices of more than 15% in 2007.
But in the northern San Joaquin Valley areas of Merced, Modesto, and Stockton, prices fell more than 15% ‐‐ the largest one‐year decline of any California metro area in at least 30 years. The 2007 declines reversed some of the rapid gains in home prices in the Central Valley early in the decade.
By September 2013, real estate prices in California’s “Inland Empire” were still 40% below their pre-crisis peak.
While the financial industry — and large parts of the country — have largely rebounded since then, there are many communities where the fallout from Lehman’s collapse and the financial crisis is still a daily fact of life, and few places more so than the Inland Empire. The local employment market continues to languish and real estate prices are still 40 percent below their precrisis peak, according to CoreLogic.
Between 2006 and 2009, Inland Empire home prices fell 53%.
Home prices in the Inland Empire fell 53 percent from the peak in 2006 to the trough in 2009. When the government-backed lender Fannie Mae sold the Giesers’ house again in 2010, it went for exactly half of the $320,000 they paid three years earlier.
In 2007, California faced a foreclosure rate nearly twice the national average.
Foreclosures increased, construction permits declined. In 2007, 1.9% of California homes were in foreclosure, nearly twice the national average of 1%. And the number of construction permits for residential units declined 35%, relative to 2006 – falling 49% from their 2004 peak.
California had the highest total number of foreclosure filings in 2008 at more than 523,000.
U.S. foreclosure filings spiked by more than 81% in 2008, a record, according to a report released Thursday, and they’re up 225% compared with 2006. […] California had the highest total number of filings for any state, 523,624, more than double 2007 levels.
In 2007, four of the top ten U.S. metro areas with the most foreclosures were in Central California.
Stockton, California now leads the nation in foreclosures. Of RealtyTrac’s top 10 metro areas for foreclosures, four are in Central California.” […] The other California cities in the top 10 were Riverside/San Bernardino (one in 33, up 198 percent), Sacramento (one in 36, up 231 percent) and Bakersfield (one in 47, up 222 percent).
For the first six months in 2007, Stockton, CA, recorded one foreclosure for every 27 households.
Stockton recorded one foreclosure filing for every 27 households during the six months ended June 30, a 256 percent increase compared with the first six months of 2006.
In some of the hardest hit regions of California, construction permits fell by more than 70% between 2004 and 2007.
In regions where prices fell most, construction nearly stopped…From 2004 to 2007, construction permits fell 60% in Riverside‐San Bernardino, 63% in Modesto, 73% in Stockton, and 76% in Merced. Permits in San Francisco in 2007 were down only 19% from the 2004 peak, and in San Jose they were down just 15% from their peak in 2005.
An estimated 68,000 construction jobs were lost by 2013 in California’s “Inland Empire.”
The construction industry has lost 68,000 jobs over the last five years, about the same amount that it gained in the decade before the collapse. Only now is there any sign of the losses reaching a bottom. ‘We’re in the beginning of the fifth year of the national expansion — and then we have the Inland Empire,’ said Jerry Nickelsburg, a forecaster in the business school at the University of California, Los Angeles. ‘It has not yet found the new engine of growth in the future. It’s in that twilight zone between its previous economy and its future economy.’